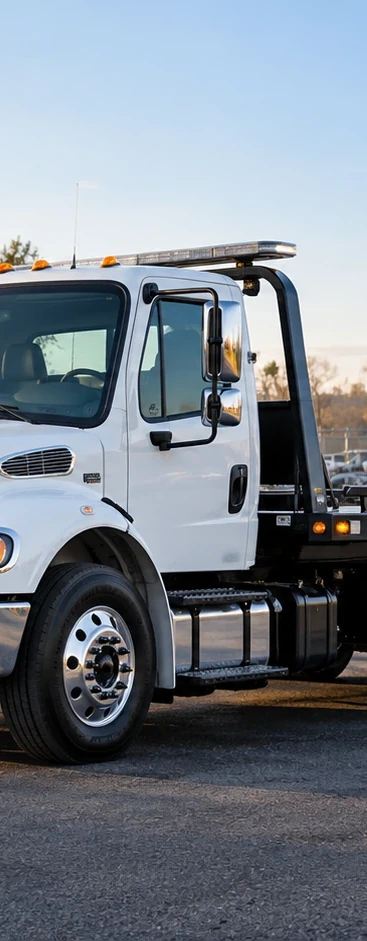
Towing & Recovery
Tow truck financing, done right
New and used rollbacks, wreckers and rotators, from dealers or private sellers. Startups and every credit profile considered.
- New, used & high-mileage
- Owner-operators welcome
- Dealer & private-party purchases
Updated October 31, 2026
Can I apply for tow truck financing with bad credit or a new business?
Yes. Avanti considers tow-truck applications from startups and across the credit spectrum. Your credit, time in business and the truck affect the down payment and available terms. Dealer and private-party purchases are welcome.
Financing by tow truck type
Rollbacks, wreckers, heavy recovery, and used units each finance a little differently. Pick the one you're buying.
- Rollback tow truck financingFlatbed and rollback carriers financed for owner-operators and fleets.
- Wrecker financingLight and medium-duty integrated, wheel-lift and self-loader wreckers, new or used.
- Rotator tow truck financingHeavy recovery rotators, financed with terms built around recovery work.
- Used tow truck financingHigher-mileage and older units, from a dealer or a private seller.
Why finance with Avanti
Buying your first rollback or adding a rotator to the fleet? We help with the equipment details, financing options, title and payment to the seller. Used and higher-mileage trucks are considered.
Your credit, time in business and the truck affect the down payment and term. Larger purchases may need a financial package; we'll tell you what to have ready.
How it works
Pick your equipment
Choose the truck or machine you need, from a dealer or a private seller, new or used.
Apply in minutes
A short application and the equipment details. We review your credit to pre-qualify, usually in just a few minutes.
Get a decision
Decisions come back in as little as 24 hours, with terms matched to your credit and time in business.
Get funded
Sign, and we coordinate funding, usually within a few days, so your equipment can get to work.
Tow truck financing at a glance
| Equipment financed | New, used and higher-mileage rollbacks, wreckers, rotators and integrated tow trucks. The term is set by the unit's age and the amount, not a blanket cutoff. |
|---|---|
| Where you can buy | Dealers, auctions and private sellers. A private-party purchase gets the same terms as a dealer deal. The title, any lien payoff and direct payment to the seller are handled for you. |
| Credit profiles | Every profile, from A-paper to challenged credit, thin credit, past (discharged) bankruptcy, and startups under two years in business. |
| Amounts and terms | $20,000 to $500,000+ with terms up to 72 months. |
| Down payment | Strong credit and time in business can mean $0 down. Challenged credit (under 600) typically pairs with 30–40% down and a 2018-or-newer truck with under 300,000 miles. Owned, titled equipment can be pledged to lower the cash at closing, and you'll know the number before you put a deposit on anything. |
| Paperwork | App-only programs with no tax returns on many deals under $300,000. Over $300,000, plan on a financial package: two years of tax returns, a balance sheet, a P&L and bank statements. Bank statements are asked for on smaller deals only when the credit profile calls for them. |
| Decision and funding | Decisions in as little as 24 hours from a short online application. Avanti coordinates funding through its lending partners, paid directly to the seller, usually within a few days, for businesses in 49 states, fully remote. |
Frequently asked questions
Can I finance a tow truck with bad credit?
Yes. We work across the full credit spectrum, from A-paper to challenged credit and startups. Lower scores typically require a down payment, and terms are tailored to your profile after we review your credit.
Can I finance a tow truck from a private seller?
Yes. Private-party purchases get the same terms as a dealer purchase. We verify the truck and the seller, coordinate any existing lien payoff, handle the title, and coordinate direct payment to the seller.
How much down payment do I need on a tow truck?
It scales with credit and time in business. Strong credit can qualify for $0 down up to a set amount; challenged credit and newer businesses typically put 20–40% down on a 2018-or-newer truck with under 300,000 miles. You'll get the exact figure for your profile before you commit to a truck, and equipment you already own can be pledged to lower it.
Related financing
- Bad credit equipment financingChallenged credit, past bankruptcies and thin files all considered.
- Startup equipment financingFirst-truck programs for businesses with no time-in-business history.
- Private party equipment financingBuy from a private seller, not just a dealer: same terms, title handled.
- Nationwide equipment financingMost U.S. states, funded remotely, no branch visit required.
Read more on this
- 7 min readHow to Finance a Tow Truck as a Startup BusinessStarting a towing company? How first-truck financing works: down payments by credit score, which truck to buy first, and what to have ready to apply.Read →
- 5 min read5 Questions to Ask Before You Finance Your Next Tow TruckBefore you sign on a wrecker or rollback, run through these five questions to protect your cash flow and get terms that actually fit a towing business.Read →
- 4 min readTow Truck Financing in 5 Steps: From Quote to KeysThe financing process from first quote to a funded tow truck, broken into five simple steps so you know exactly what to expect.Read →